Buy Now, Pay Later: Is It a Smart Financial Move for You?
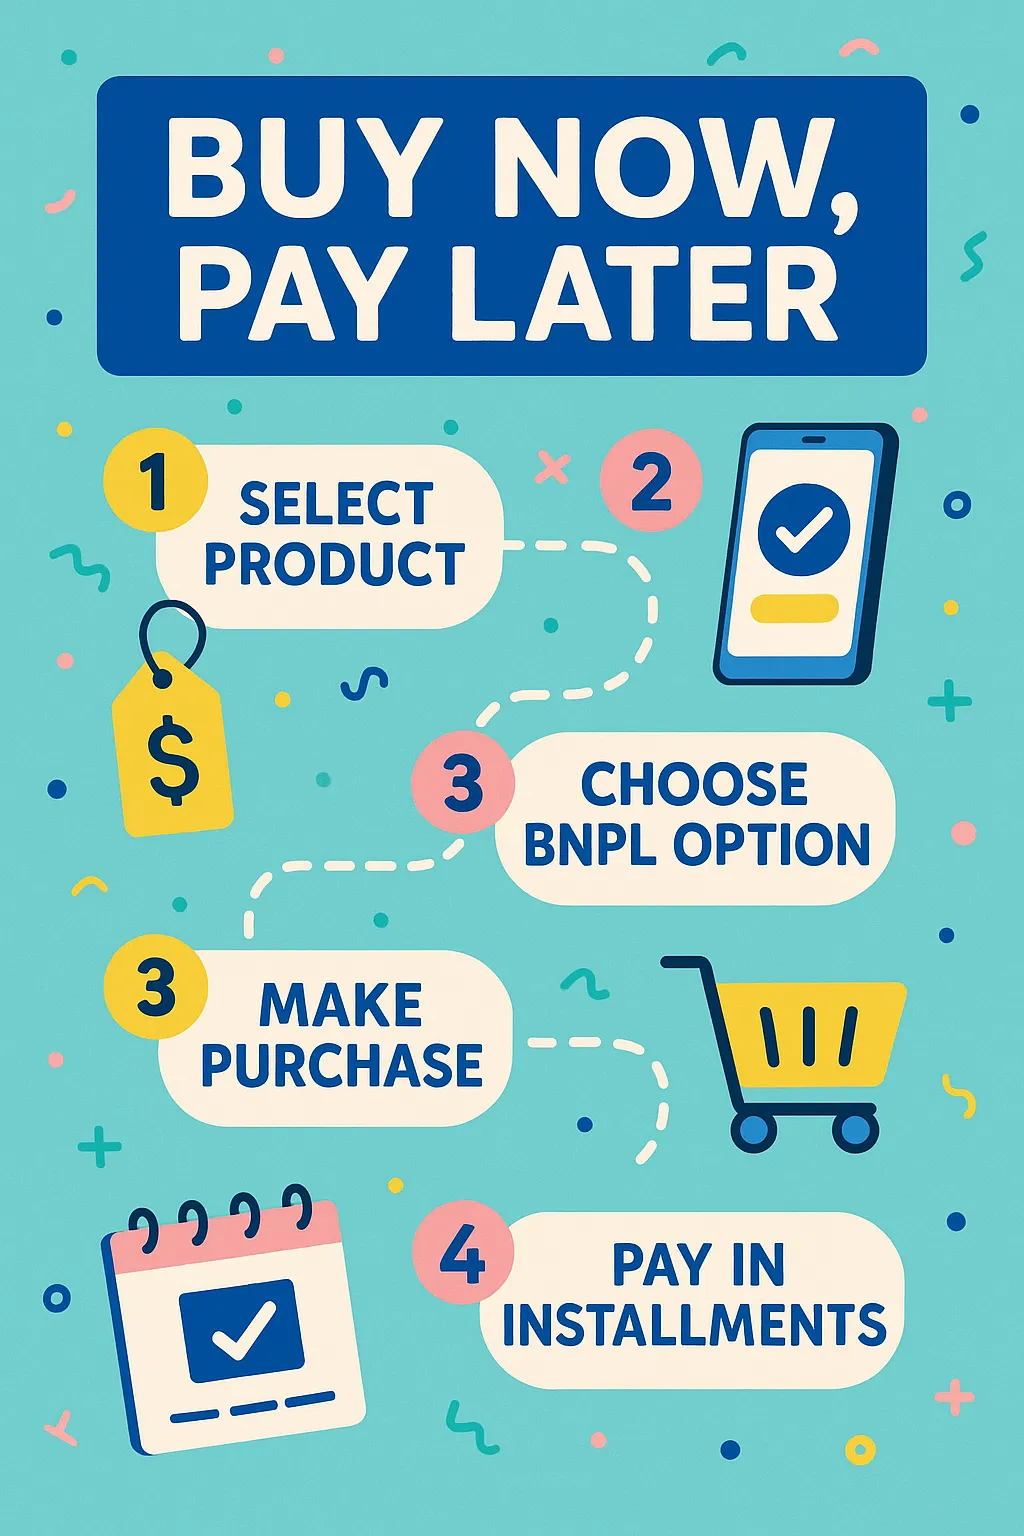
Understanding Buy Now, Pay Later and How It Works "Buy Now, Pay Later" ( BNPL ) services have transformed the retail landscape. They provide consumers with the flexibility to make purchases immediately and pay over time, often without interest. Companies like Klarna, Afterpay, and Affirm are leading this charge. These options are especially popular among younger generations, who prefer flexible payment methods. But is BNPL genuinely beneficial, or does it come with hidden risks? The Appeal...
Understanding Buy Now, Pay Later and How It Works
“Buy Now, Pay Later” (BNPL) services have transformed the retail landscape. They provide consumers with the flexibility to make purchases immediately and pay over time, often without interest. Companies like Klarna, Afterpay, and Affirm are leading this charge. These options are especially popular among younger generations, who prefer flexible payment methods. But is BNPL genuinely beneficial, or does it come with hidden risks?
The Appeal of BNPL for Millennials and Gen Z
The rise of BNPL isn’t a coincidence. Millennials and Gen Z shoppers gravitate towards this payment method for several reasons. It offers them immediate gratification and budget flexibility. Research reveals that over half of these younger consumers have used a BNPL service at least once. Let’s take a closer look at what makes it so appealing.
Instant Gratification
Today’s consumers thrive on immediate results. BNPL caters to this craving by allowing instant purchases without the burden of full upfront payments. The convenience of this payment method is compelling, especially for digital natives who cherish seamless experiences.
No Interest (Usually)
Most BNPL services don’t charge interest, which makes them a popular alternative to traditional credit card payments. As long as payments are made on time, users can avoid fees, making BNPL a seemingly safer and more manageable option.
Potential Risks of Using BNPL
While there are benefits, BNPL can also pose financial risks if not used wisely. Here are some critical concerns to ponder before opting in.
Overspending
The convenience of BNPL can lead consumers to spend more than they planned. Small payments might seem manageable at first, but they can quickly accumulate, leading to significant debt burdens.
Hidden Fees and Penalties
Although most BNPL companies promote interest-free payments, late fees can be steep. It is essential to read the fine print to avoid any unexpected costs or financial surprises.
Impact on Credit Score
Many users overlook how BNPL can affect their credit. Missed payments can harm credit scores, limiting future financial opportunities. Understanding this risk is essential before committing to a BNPL agreement.
How to Use BNPL Responsibly?
Deciding to use BNPL services necessitates a responsible approach. Here are some valuable tips for managing your payments effectively:
Set Clear Budgets
Before making any purchase, evaluate your budget thoroughly. Make sure you use BNPL only for essential items or planned purchases. This strategy will help you avoid impulsive decisions that might strain your finances.
Understand the Terms and Conditions
Always read the full agreement prior to entering a BNPL plan. Be aware of payment due dates, late fees, and other potential penalties. Knowledge empowers you to make informed financial choices.
Keep Track of Your Payments
Managing multiple BNPL agreements can become cumbersome. Utilize budgeting apps or set reminders to ensure you never miss a payment. Staying organized is key to avoiding unnecessary financial pitfalls.
Is BNPL Suitable for You?
Determining the suitability of BNPL for you hinges on your financial habits and self-discipline. If you are conscientious about making repayments, BNPL can offer significant financial flexibility without accruing interest. Conversely, if you tend to make impulsive purchases or struggle to meet payment deadlines, this method may not be the best fit.
Alternatives to BNPL
If you are hesitant about using BNPL, several alternatives may align better with your financial goals:
- Traditional Credit Cards: They offer more transparency and potential rewards for usage.
- Personal Savings: This indicates a more cautious financial strategy, helping you avoid debt altogether.
- Low-Interest Personal Loans: These can be ideal for larger, necessary purchases that require financing.
Conclusion: Balance Convenience with Caution
BNPL presents a powerful tool for managing your finances when used wisely. It’s important to understand both its advantages and disadvantages to make informed decisions. Always prioritize financial discipline and transparency, allowing you to enjoy the benefits without falling into unnecessary debt.
One time, consider how “financial flexibility” can enhance your budgeting strategy.
References: